Texas · Home insurance
Insuring Jewelry, Watches and Valuables: When a Homeowners Policy Is Not Enough
Your homeowners or renters policy does cover jewelry, but only up to a low limit and only for certain kinds of loss. Here is how to find your limit, and how scheduling an item closes the gap.

In short
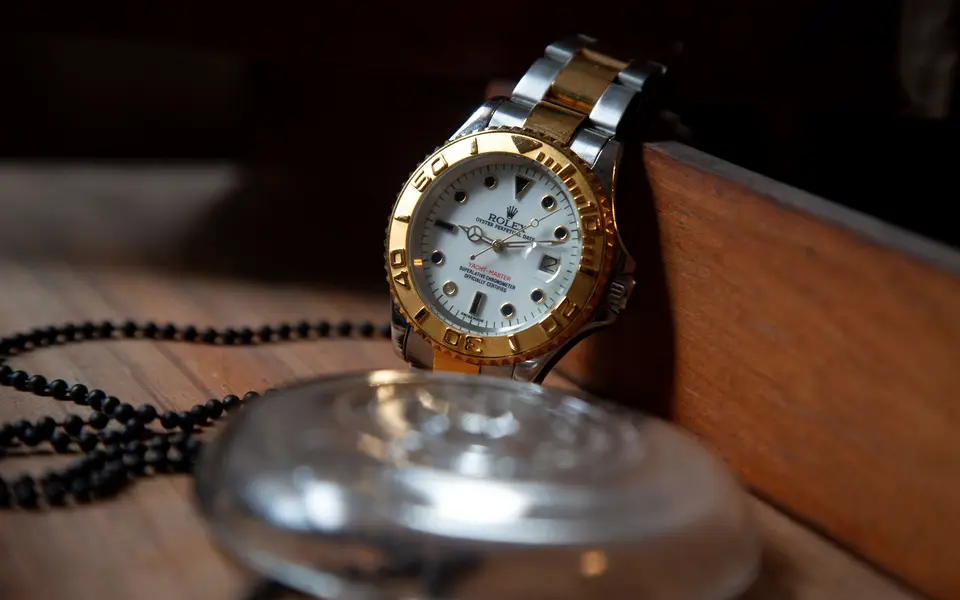
A standard homeowners policy covers jewelry, watches and furs, but with a special limit. The Insurance Information Institute says the limit for theft of jewelry is generally $1,500, and a lost or dropped item is typically not covered at all. To insure a ring, watch or collection for its real value, you either raise the limit or schedule each item on a floater, which lists the piece with its appraised value and covers more kinds of loss.
- Homeowners and renters policies cover jewelry only up to a special limit, which is separate from your overall personal property limit.
- The Insurance Information Institute says the standard theft limit for jewelry is generally $1,500. Some policies are lower.
- Simply losing a ring or leaving a watch in a hotel room is typically not covered by a homeowners policy.
- Scheduling an item (a floater) lists it by name and value and covers more kinds of loss, including accidental loss.
- You need a professional appraisal to schedule an item, and the value should be updated over time.
In this article
- Does a homeowners policy cover jewelry at all?
- What kinds of jewelry loss are not covered?
- What are your options for closing the gap?
- What is scheduled personal property, and how does a floater work?
- What do you need to schedule a ring or watch?
- Which valuables are worth scheduling?
- How does this play out? A worked example
- How do you keep the coverage accurate over time?
Service: Home & Personal Insurance in Flower Mound, Plano and Garland
You own an engagement ring, a good watch or a few inherited pieces, and you assume your home insurance covers them. It does, but only up to a small limit and only for certain kinds of loss. If a piece is worth more than that limit, you need to raise the limit or schedule the item by name.
Does a homeowners policy cover jewelry at all?
Yes. The Insurance Information Institute explains that a standard homeowners policy includes coverage for jewelry and other precious items such as watches and furs. They are part of your personal property, alongside furniture, clothing and electronics.
The catch is a feature called a special limit. Your policy may show a personal property limit of $150,000 or more, but inside that number are much smaller caps for certain categories. The Texas Department of Insurance (TDI) says it simply: policies limit what they will pay for jewelry and art, and you should talk to your agent about added coverage.
For jewelry, the Insurance Information Institute says the standard policy generally caps theft losses at $1,500. That is the total for all the jewelry taken in one theft, not $1,500 for each piece. Some policies are lower. TDI's renters insurance guidance gives $500 for jewelry and watches as an example of a limit you might find.
So the first job is to find your own number. Look in the personal property section of your policy for a heading such as "special limits of liability." If you cannot find it, ask. For a wider view of what your policy does and does not include, see what homeowners insurance covers in Texas.
What kinds of jewelry loss are not covered?
The dollar limit is only half of the gap. The other half is the cause of the loss.
A homeowners policy pays for personal property damaged or lost because of the perils the policy covers, such as fire, windstorm, theft and vandalism. A peril is the insurance word for a cause of loss, and you can find it and similar terms in our insurance glossary.
Many of the ways people actually lose jewelry are not on that list. The Insurance Information Institute gives two examples of accidental losses that homeowners coverage typically excludes: a ring dropped down the drain and a watch left in a hotel room.
How a standard homeowners policy typically treats common jewelry losses:
| What happened | Standard homeowners policy | Scheduled floater |
|---|---|---|
| Stolen in a burglary at home | Covered, up to the special limit | Covered, up to the scheduled value |
| Destroyed in a house fire | Covered, subject to the policy's limits | Covered, up to the scheduled value |
| Ring slipped off at the lake and was never found | Typically not covered | Typically covered |
| Watch left behind in a hotel room | Typically not covered | Typically covered |
| Stone fell out of the setting | Typically not covered | Often covered, check the wording |
| Gradual wear, scratches | Not covered | Not covered |
What this means for you: if your main worry is losing a ring rather than a burglary, raising a theft limit does not solve your problem. Only coverage that includes accidental loss does.
What are your options for closing the gap?
There are three, and they are not equally strong.
Option 1: Leave it as it is. This is reasonable when your jewelry is worth less than your policy's special limit and you can absorb an accidental loss yourself.
Option 2: Raise the special limit. The Insurance Information Institute calls this the less expensive option. You pay to increase the jewelry limit on your existing policy. There are still caps, both overall and per piece. The Institute's example is a $5,000 overall limit with no more than $2,000 for any single piece. And the coverage still applies only to the perils the policy lists.
Option 3: Schedule the items. Each piece is listed individually with its value, either on an endorsement to your policy or on a separate floater policy. The premium is higher, but the coverage is broader. According to the Institute, a floater covers losses of any type, including accidental ones.
The three options side by side:
| Leave as is | Raise the limit | Schedule the item | |
|---|---|---|---|
| Typical theft limit | About $1,500 for all jewelry | Higher, with a cap per piece | The appraised value of each piece |
| Accidental loss | Typically not covered | Typically not covered | Typically covered |
| Appraisal needed | No | Usually not | Yes |
| Cost | Nothing extra | Lower | Higher |
| Best fit | Modest jewelry | Several mid-value pieces | One or more high-value pieces |
What this means for you: match the option to the piece. A $1,200 watch is fine under the standard limit. A $9,000 ring is not, and a raised limit with a $2,000 cap per piece would not cover it either.
What is scheduled personal property, and how does a floater work?
"Scheduling" means writing an item onto the policy by name. The NAIC describes a scheduled personal property endorsement, also called a personal article floater, as coverage for jewelry, furs, stamps, coins, guns, computers, antiques and other items whose value might be greater than the normal limits in your homeowners policy.
The schedule is a list. Each line has a description of the item and a dollar amount. That amount, not the special limit in your base policy, is the most the insurer will pay for that item.
The word "floater" comes from the idea that the coverage floats with the item wherever it goes, instead of being tied to your house. That is why it suits things you wear and carry.
Three questions to ask before you buy:
- How is a loss settled? Some coverages pay the scheduled amount. Others repair the piece or replace it with one of like kind and quality, up to the scheduled amount.
- Does a deductible apply? It varies. Ask, and compare it with your homeowners deductible.
- What is excluded? Wear and tear and intentional loss are typically excluded. Read the list.
What do you need to schedule a ring or watch?
The process is short, and most of it is paperwork you only do once.
- Find your current limit. Read the special limits in your homeowners or renters policy so you know which pieces exceed it.
- List the candidates. Write down each piece that is worth more than the limit, or that you could not afford to replace.
- Get a professional appraisal. The Insurance Information Institute says items must be professionally appraised before you buy a floater. Ask for a written appraisal that describes the metal, the stones, their size and quality, any serial number, and a stated value.
- Photograph each piece. Take clear photos from several angles, including any engravings or serial numbers.
- Keep the receipts. Store the receipt, appraisal and photos together.
- Send it all to your agent. Ask for the item to be scheduled and confirm the date the coverage starts.
- Check the declarations page. Make sure each piece appears with the right description and amount.
Steps 4 and 5 are also the core of a good household record. TDI recommends keeping your inventory and the receipts for major items in a fireproof place or at another location. Our guide shows how to make a home inventory in one afternoon.
Which valuables are worth scheduling?
Jewelry is the usual reason people ask, but the same logic applies to anything with a special limit or a high value in a small package.
- Engagement and wedding rings. Worn daily, easy to lose, and often the single most valuable item a person owns.
- Watches. Travel with you and are a common target for theft.
- Inherited pieces. Often never appraised, so nobody knows whether the limit is enough.
- Collections. Coins, stamps and similar collections are on the NAIC's list of items that often exceed normal limits.
- Firearms. Also on the NAIC's list.
- Art, antiques and instruments. TDI specifically names art alongside jewelry as a limited category.
If you use expensive equipment to earn money, such as cameras or tools, the answer may be on the business side instead. A homeowners policy is not designed for business property. See running a business from home in Texas or ask about commercial insurance.
Renters have the same exposure as owners. If you rent an apartment and own one good ring, the special limit in a renters policy applies to you. Read what renters insurance covers in Texas.
How does this play out? A worked example
This is an illustration with round numbers, not a quote or a promise of how any claim will be paid.
You own an engagement ring appraised at $9,000. Your homeowners policy has a $1,500 special limit for theft of jewelry and a $2,500 deductible.
Scenario 1: The ring is stolen in a burglary, and it is not scheduled. The most the policy pays for the ring is the $1,500 special limit. Depending on what else was stolen and how your deductible applies, your share of the ring's loss is at least $7,500.
Scenario 2: The ring slips off while you are swimming, and it is not scheduled. This is an accidental loss, which a homeowners policy typically does not cover. The likely payment is nothing, and the loss is $9,000.
Scenario 3: You raised the jewelry limit to $5,000 with a $2,000 cap per piece. For a theft, the policy pays up to $2,000 for the ring. For the swimming loss, the answer is still typically nothing.
Scenario 4: The ring is scheduled for $9,000. For the burglary or the swimming loss, the coverage responds up to the scheduled $9,000, according to its settlement terms and any deductible on the schedule.
The lesson is in Scenario 3: a higher limit does little for one expensive piece and nothing for accidental loss.
How do you keep the coverage accurate over time?
A schedule is only as good as the values on it. Prices of gold and stones change, and so does what you own.
- Update appraisals. Ask how old an appraisal can be, and have high-value pieces reappraised from time to time so the scheduled amount matches the cost to replace them.
- Add new pieces promptly. A gift or an anniversary upgrade is not covered at its full value until it is on the schedule.
- Remove what you no longer own. If you sell or give away a piece, take it off so you stop paying for it.
- Review at renewal. Check the schedule each year when you review your policy. If the premium is a concern, see what actually moves the price of homeowners insurance before cutting coverage.
- Report a loss quickly. If something is stolen, file a police report and tell your insurer as soon as possible.
How Assured Insurance Group helps
Assured Insurance Group helps people in Flower Mound, Plano, Garland and across Dallas–Fort Worth with home and personal insurance, including coverage for jewelry and other valuables. We will walk through your current policy with you, find the special limits that apply to your belongings, and go over your options for raising a limit or scheduling an item. You can visit the Plano office, email info@assuredinsgroup.com, or review the rest of your home insurance at the same time. To get started, request a quote or call 214-222-5234.
Questions people ask next
Does homeowners insurance cover a lost engagement ring?
Usually not. A homeowners policy covers jewelry against the causes of loss it lists, such as fire and theft. According to the Insurance Information Institute, accidental losses such as dropping a ring down a drain or leaving a watch in a hotel room are typically excluded. A scheduled floater is the coverage designed to pay for that kind of loss.
Does renters insurance cover jewelry?
Yes, with the same kind of special limit. The Texas Department of Insurance notes that some renters policies cap payments for certain property and gives $500 for jewelry and watches as an example. If you rent and own a valuable ring or watch, check the limit in your policy and ask about scheduling the item.
Do I need an appraisal to insure jewelry?
For a scheduled floater, yes. The Insurance Information Institute says items must be professionally appraised before you buy a floater. The appraisal describes the piece in detail and states its value, and that description is what the insurer relies on if the item is lost. A sales receipt alone may not be enough.
What other valuables can be scheduled?
The NAIC lists jewelry, furs, stamps, coins, guns, computers, antiques and other items whose value might be greater than the normal limits in a homeowners policy. Fine art, musical instruments, cameras and collectibles are commonly handled the same way. Ask which categories your policy limits, because the list varies from one policy to another.
Is jewelry covered when I travel?
Personal property coverage generally follows your belongings away from home, so a covered theft while traveling can be paid up to the special limit. A scheduled floater typically goes further and covers accidental loss as well. Before a trip, check whether your coverage has any territory restrictions and keep photos of the pieces you take.
Will a jewelry claim affect my homeowners policy?
A claim under your homeowners policy becomes part of your claims history, which insurers look at when they price and renew policies. In Texas an insurer cannot raise your premium for claims other than appliance-related water damage unless you file two or more claims within three years. Ask how a scheduled item claim is recorded with your insurer.
Sources and further reading
- Insurance Information Institute: Do I need special coverage for jewelry and other valuables?
- NAIC: A Consumer’s Guide to Home Insurance
- Texas Department of Insurance: Home insurance guide
- Texas Department of Insurance: Renters insurance in Texas
- Texas Department of Insurance: Consumer Bill of Rights, Homeowners, Dwelling and Renters Insurance
General information for Texas readers, current as of August 2026. It is not legal, tax or insurance advice. Your coverage depends on the wording of your own policy.
More home insurance guides
- Your Homeowners Claim Was Denied in Texas: What You Can Do Next
- Your Homeowners Insurance Was Non-Renewed in Texas: Your Rights and Next Steps
- The Texas FAIR Plan: Home Insurance When No Company Will Cover You
- Frozen and Burst Pipes in a Texas Winter Storm: What Insurance Covers
- Tornado Damage in North Texas: What Your Home Insurance Pays For
- Pools, Trampolines and Dogs: How They Affect Your Home Insurance Liability